A hail or wind storm can leave a roof damaged in ways nobody on the ground can see. For many homeowners in Leander and across Central Texas, the next question is whether to file an insurance claim and how the process works. This guide walks through it step by step, so you know what to expect before you call anyone.
One thing to keep in mind from the start: your insurance company decides what your policy covers. A roofer's job is to find and document the damage clearly, so you and your insurer are looking at the same evidence.
Right After the Storm
The first hours after a storm are about safety and record keeping, not repairs.
- Stay off the roof. Wet or damaged shingles are slippery, and a fall is a far bigger problem than a leak.
- Take photos from the ground. Dented gutters, torn screens and shingles in the yard are all worth a picture.
- Protect the inside. Put a bucket under any drip and move furniture away from wet spots.
- Write things down. Note the date of the storm and keep receipts for any emergency cleanup.
- Check your policy. Every policy sets its own rules and deadlines for reporting damage. If you are unsure, call your insurance agent.
If you are not sure what storm damage looks like, our post on how to spot hail damage on your roof covers the signs to watch for.
Should You Call Your Insurer or a Roofer First?
Many homeowners call a roofer first. A free inspection shows whether there is storm damage worth reporting at all. If the inspection finds functional damage, you file the claim with your insurer and the roofer's report goes to the adjuster. If the damage is minor or only cosmetic, you can decide what to do with the facts in hand instead of guessing.
Either way, keep an eye on the reporting deadline in your policy.
Step One: A Free Roof Damage Inspection
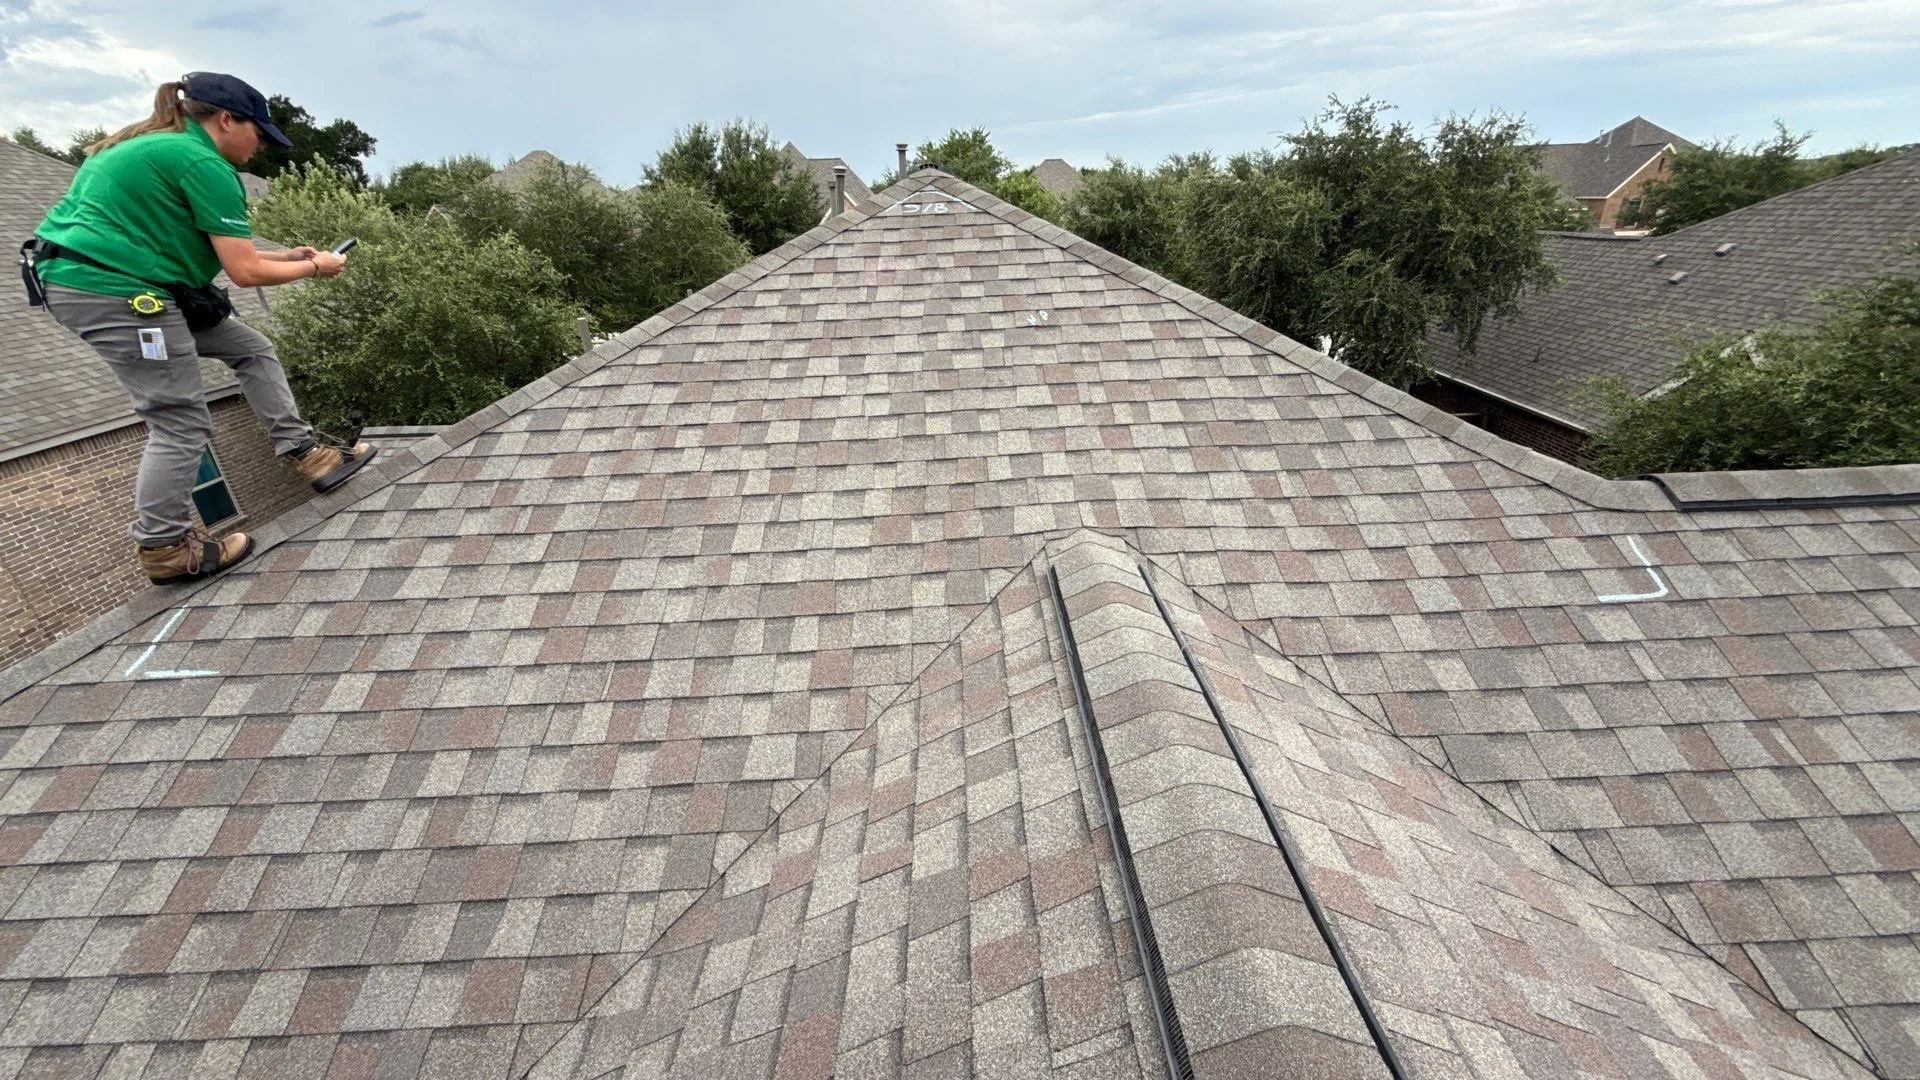
The Kerusso Roofing & Construction starts every storm claim with a free roof damage inspection. We look for hail impacts, granule loss, damaged vents and gutter issues, and every finding is documented with photos and notes.
The inspection costs nothing whether or not you decide to file a claim. If it finds nothing worth claiming, there is no charge.
Step Two: A Detailed Damage Report
Next, the findings become a clear report. The most important thing the report does is separate functional damage from cosmetic damage, because that is what an adjuster reviews.
- Functional damage weakens how the roof keeps water out. Cracked shingles, heavy granule loss and broken seals or flashing are examples.
- Cosmetic damage changes how the roof looks without affecting how it performs, such as a shallow dent in a metal vent cap.
A report built on photos and notes gives you facts to share with your insurer.
Step Three: Working With Your Adjuster
We submit the report to your adjuster. When it is needed, we also meet the adjuster at your home and walk through the damage we documented. That visit helps make sure covered damage is included in the review. The adjuster and your insurance company still make the final decision on what your policy pays for.
What Happens After the Claim Is Reviewed
Once the claim is reviewed, the work itself begins, and the right fix depends on what the inspection found.
Limited damage often calls for a targeted repair. Wind damage repair can mean replacing lifted or missing shingles, resealing loose tabs and resetting bent flashing so water runs off the way it should. Our roof repair in Leander page covers those smaller fixes.
Widespread hail damage across several roof planes is a different job. In that case the result may be a full roof replacement, with the old roof torn off and a new one installed. We work with shingle, metal, slate and tile, so the new roof can match what your home had before the storm. Our roof replacement in Leander page explains a full tear-off, and our post on deciding between repair and replacement goes deeper on that choice.
Every roofing job we complete carries a 7-year labor warranty.
What Affects Your Out-of-Pocket Cost?
Your cost on a storm claim depends mostly on your policy:
- Your deductible, which your insurance company sets and writes into your policy.
- What the insurer covers, decided after its adjuster reviews the roof.
- The roof itself: its size and pitch, the roofing material, and any damage to decking, vents or gutters found during the work.
- Upgrades you choose. If you pick something the policy does not cover, such as a different material, that difference is yours to pay.
We explain every line of the quote before any work starts, with no hidden costs or surprise add-ons.
Why a Careful Roofer Matters on a Claim
A storm claim goes better with a roofer who documents carefully and tells you the truth about what the roof needs. The Kerusso Roofing & Construction brings more than 13 years of roofing experience to every inspection. We are locally owned and operated in Leander, and licensed, bonded and insured.
You get an honest recommendation, whether that is a small repair, a full replacement or no claim at all. Our full roof insurance claims page has more detail on how we help.
Schedule a Free Storm Damage Inspection
Hail and wind damage tends to grow with every rain that follows. Call The Kerusso Roofing & Construction at (737) 231-3564, Monday through Friday, 7am to 7pm, or request a free roof inspection online, and we will document your roof before you talk to your insurer.